
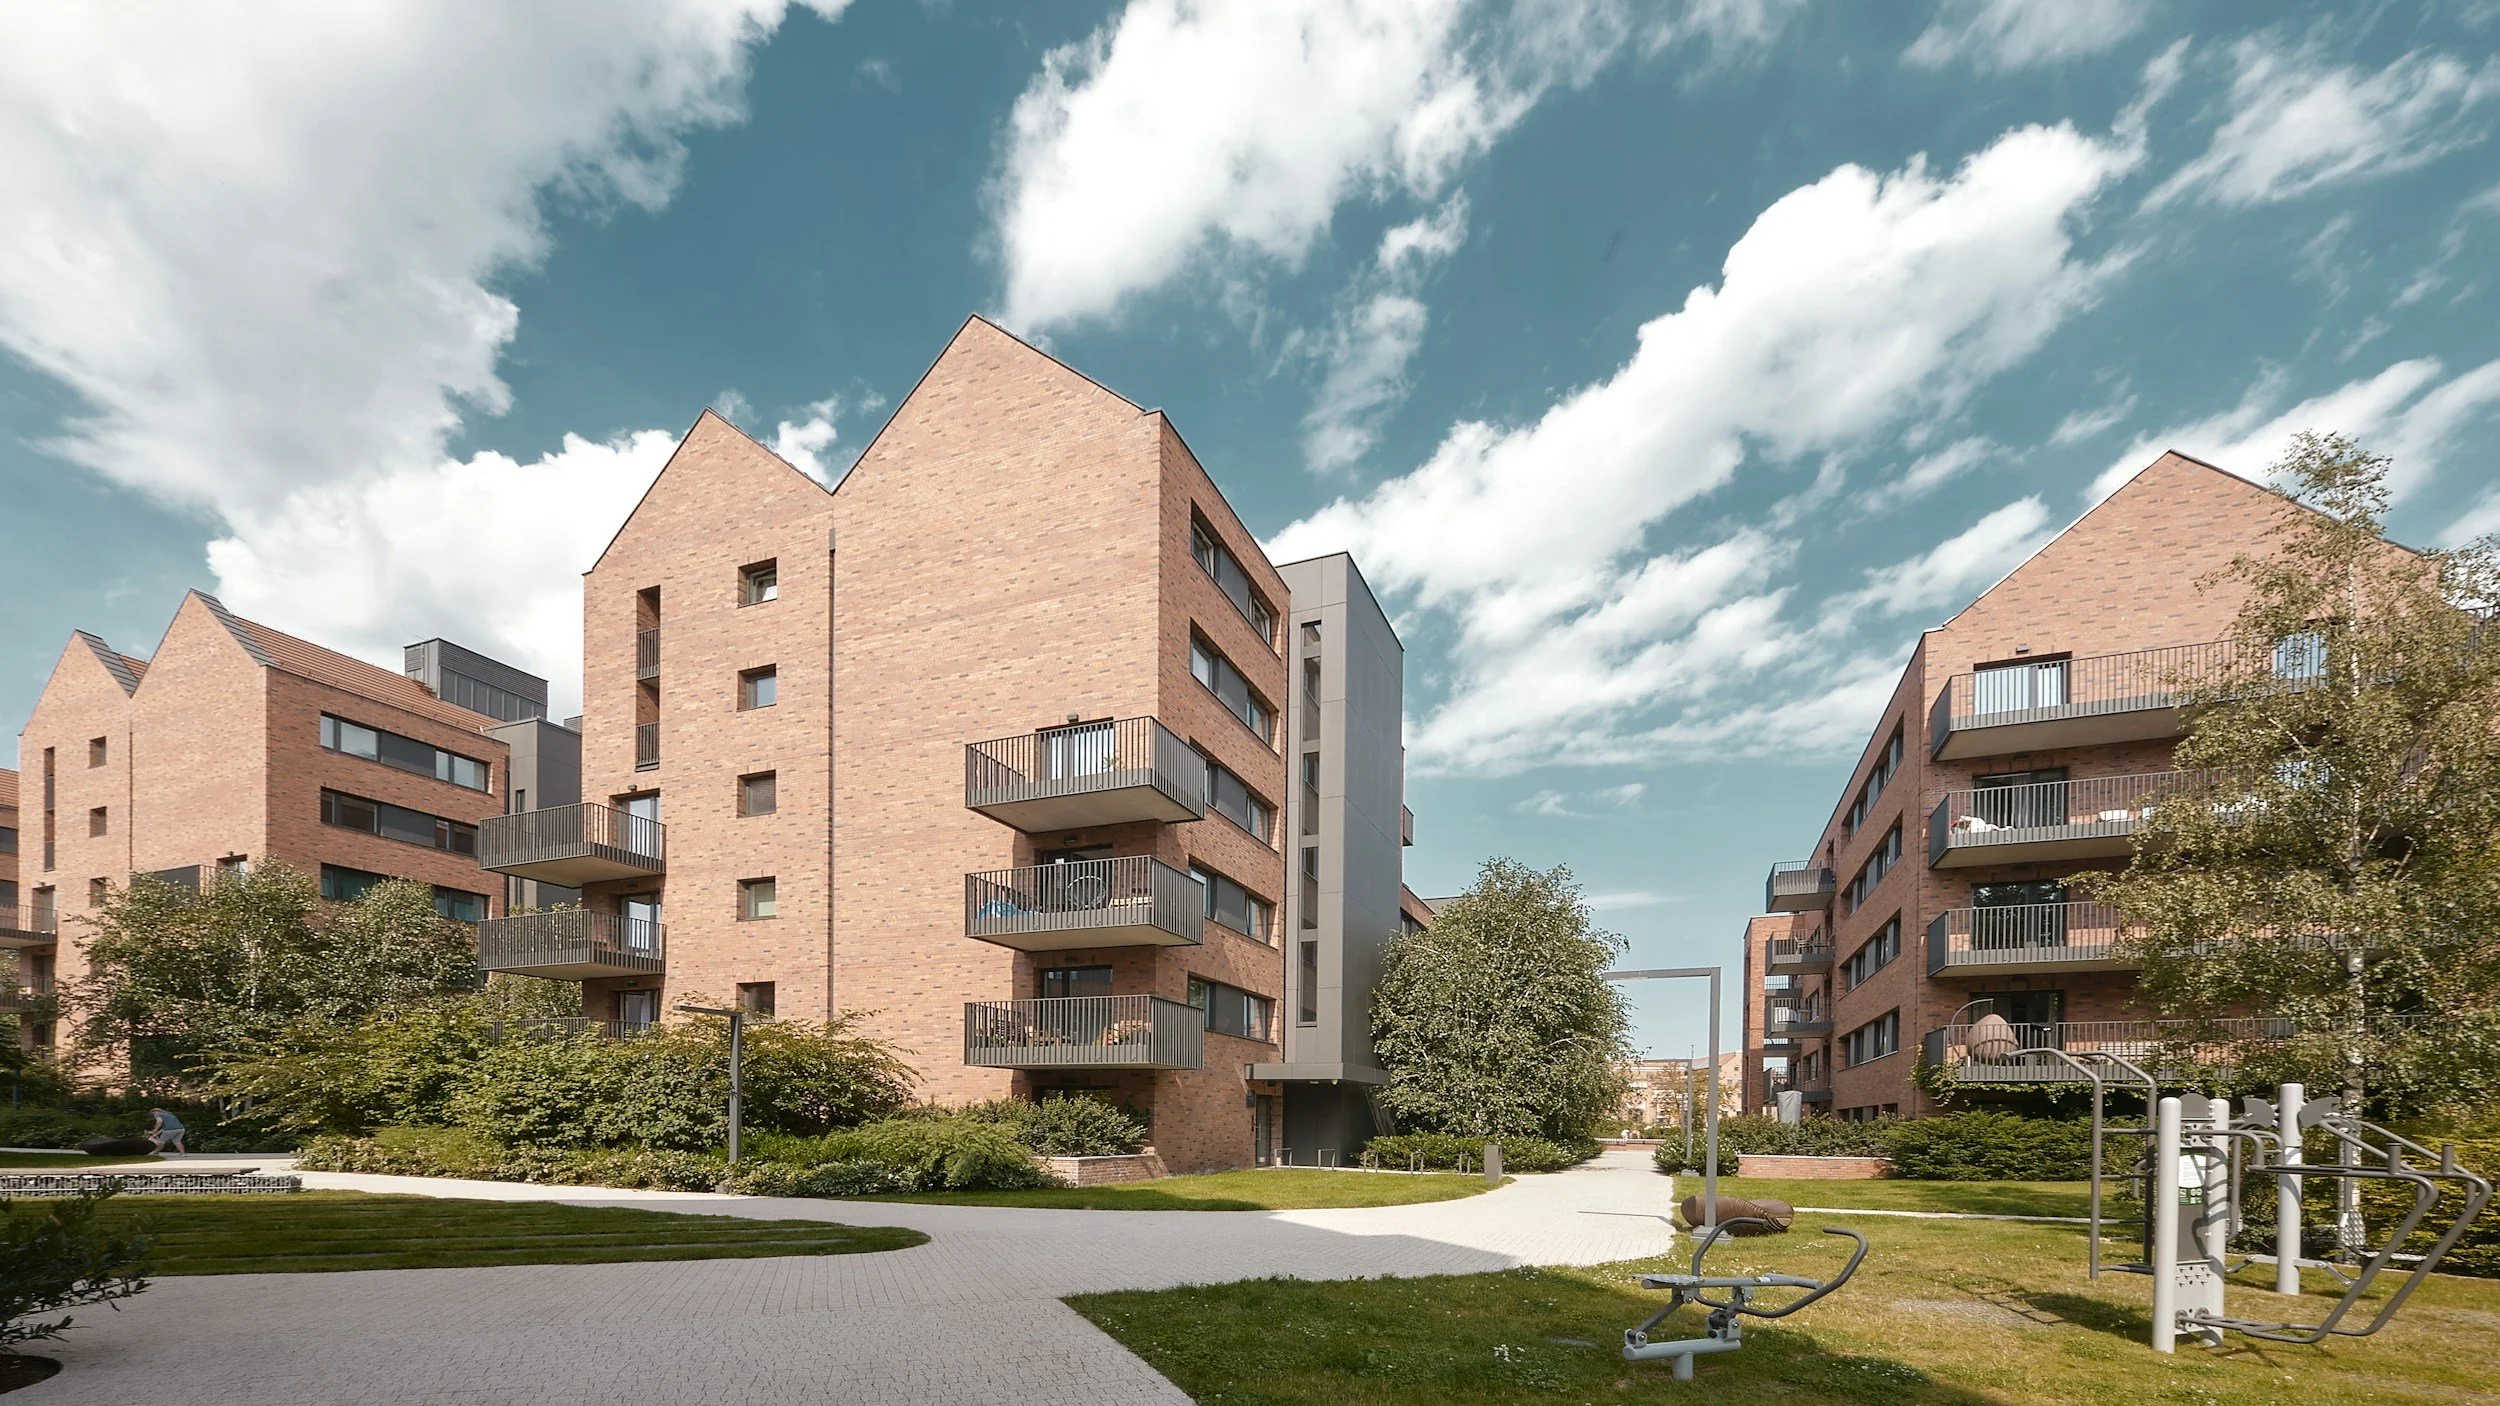
Short-term Acquisition and Renovation Financing for Multifamily Properties.
A business-purpose program for experienced investors acquiring and renovating multifamily properties with five or more units.
Program at a Glance
Multifamily 5+ Units: Acquisition and Renovation
- Property type: Multifamily with 5+ units.
- Purpose: Acquisition and renovation.
- Loan amount: $125,000+.
- Leverage: Up to 80% loan-to-cost and 77% after-repair value.
- Term: 6–24 months.
- Minimum FICO: 650.
- Experience: Investors with 3–5 successfully completed projects.
- Ground-up construction: Considered case by case.
Guidelines Brokers Should Know
Leverage and Valuation
- The requested loan must fit both the loan-to-cost and after-repair-value limits. A deal within one limit may still be reduced by the other.
- The after-repair value estimate should be supported by the renovation scope, budget and timeline.
Sponsor and Exit
- Sponsors should show successfully completed projects comparable to the planned work. Comparability and documentation are subject to program review.
- Explain the planned exit: sale, refinance or stabilization.
Have a deal that fits?
Send us the property, requested loan amount, renovation budget, after-repair value estimate, sponsor experience and planned exit. We’ll review the scenario and let you know if it fits.
Download the loan program details.
Frequently Asked Questions
What is a multifamily value-add loan?
Kirkland’s Multifamily 5+ Unit Value-Add program is short-term acquisition-and-renovation financing for multifamily properties with five or more units. It is built for a renovation or repositioning plan and stabilization, not necessarily an immediate sale.
What experience does a borrower need for a multifamily value-add loan?
The current program guideline is 3-5 successfully completed projects. Project comparability and documentation are subject to program review.
Can a borrower use a value-add loan for ground-up construction?
Ground-up construction is not automatically eligible; it may be considered case by case.
Can a borrower use a value-add loan on a stabilized property?
This program is for acquisition and renovation. If the property is already stabilized and meets the DSCR, credit and ownership criteria, the Commercial DSCR program may be a better fit.
What is the maximum leverage on a multifamily value-add loan?
Leverage is up to 80% of cost and 77% of after-repair value, and the loan must fit both limits. These are maximums, not guarantees. Approved leverage depends on the sponsor, property, budget, valuation and full underwriting.
Don’t have a deal that fits?
See how Kirkland reviews a loan from initial scenario through closing.